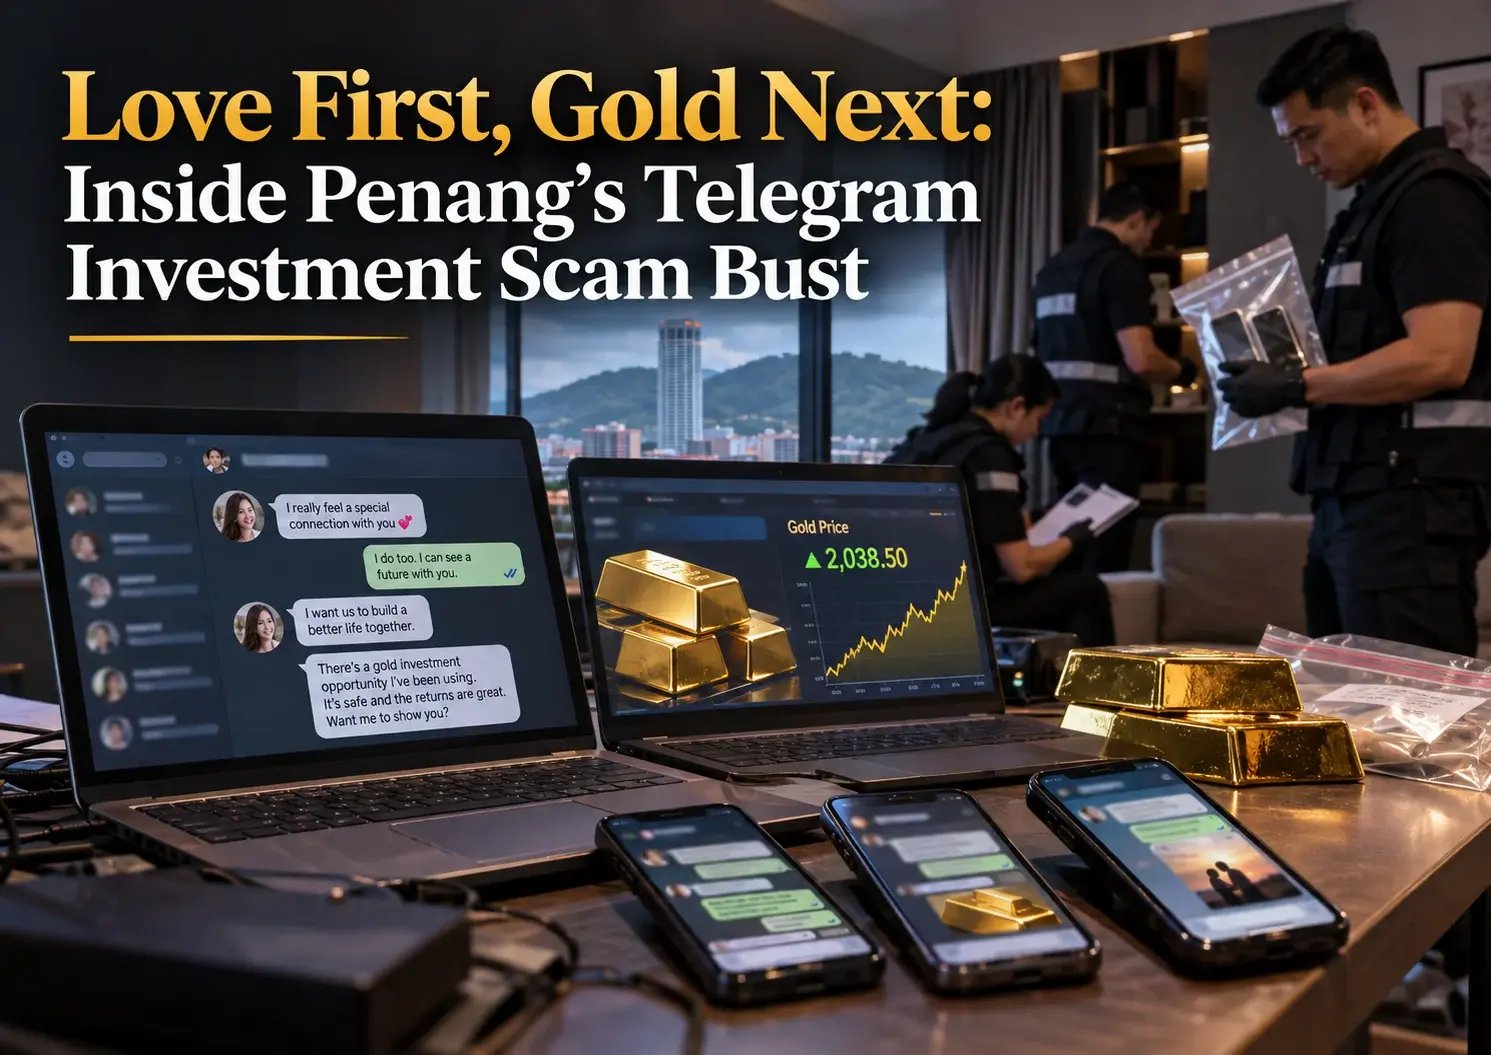
Love First, Gold Next: Inside Penang’s Telegram Investment Scam Bust

A scam does not always begin with money. Sometimes, it begins with attention, conversation and trust.
That is the pattern behind a recent case in Bayan Lepas, Penang, where Malaysian police arrested 35 foreign nationals suspected of operating an online love-scam and gold-investment scam centre.
Police said the syndicate had allegedly been operating since September and was targeting Chinese women through Telegram. During raids on two houses, investigators seized 119 mobile phones and three laptops believed to have been used in the scam activities.
What makes the case particularly relevant for financial institutions is the way two forms of deception can reinforce each other. A relationship can establish trust first. An investment opportunity introduced later may then appear more credible because it comes from someone the victim believes they know.
But the financial crime risk does not end with the manipulated customer. The romance is effectively the acquisition channel. The wider risk emerges when authorised victim payments begin flowing into beneficiary accounts, mule networks or connected recipients that can collect and move the proceeds at scale.
For banks and payment firms, the challenge is therefore two-sided: recognise when a customer's behaviour changes under social engineering, and identify when the account receiving the money is part of a broader scam network.
What Happened in Penang?
Police raided two houses in Bayan Lepas on 2 November 2026, arresting 35 foreign nationals aged between 18 and 46.
The suspects were detained on suspicion of operating an online love-scam and gold-investment fraud syndicate. Police said initial investigations indicated that the operation had been active since September and targeted Chinese women using Telegram.
Officers recovered 119 mobile phones and three laptops with chargers, with the seized equipment valued at around RM60,000. The case is being investigated for cheating and criminal conspiracy.
Police also warned the public to be cautious when strangers on social media or messaging platforms attempt to establish relationships before introducing investment opportunities promising lucrative returns.
The available reporting does not specify how much victims lost, which payment methods were used or how the proceeds were ultimately moved. Those details should therefore not be assumed.
What the case does reveal is the structure of the deception: relationship-building and investment solicitation can operate as parts of the same scam journey.
When Trust Becomes the Entry Point to Investment Fraud
Love scams and investment scams are often treated as separate categories.
Cases like this show why that distinction can be misleading.
A relationship can become the mechanism that makes the investment pitch believable. Instead of approaching the victim immediately with a financial opportunity, the scammer can spend time creating familiarity and emotional trust before introducing money into the conversation.
That changes the risk for financial institutions.
A customer sending money in this situation may not believe they are dealing with an unknown investment promoter. They may believe they are acting on advice from a trusted romantic interest.
Authentication may therefore work exactly as intended. The customer logs in, confirms the beneficiary and authorises the transfer personally.
The weakness lies elsewhere: the customer has been socially engineered into believing the transaction is legitimate.
This is why detecting scams increasingly requires more than determining whether a transaction was authorised. Institutions also need to understand whether the payment represents an unusual behavioural change and whether the beneficiary receiving the funds displays characteristics associated with scam collection or mule activity.
The Beneficiary Can Tell a Different Story
On the victim side, a transfer may look voluntary and explainable.
The beneficiary side can reveal something very different.
An account receiving investment-related payments from multiple unrelated individuals, particularly when the account holder has no clear economic reason for receiving them, may warrant closer examination.
The pattern becomes stronger when incoming funds are followed by rapid transfers, withdrawals or movement towards connected accounts.
Network relationships also matter. Multiple beneficiaries may share devices, contact details, counterparties or transaction patterns even when they appear unrelated on paper.
This is particularly relevant to organised scam centres. The person building the relationship with the victim does not necessarily own or control the account receiving the money. Different people can perform different roles across recruitment, communication, collection and movement of proceeds.
That creates a critical financial crime lesson: the victim interaction may be highly personal, but the proceeds infrastructure can be highly organised.
What Banks and Payment Firms Should Watch
Romance-led investment scams can generate signals on both sides of the payment.
Banks should pay attention when customers suddenly begin transferring money to unfamiliar investment-related beneficiaries, particularly where payment values escalate or behaviour changes significantly from historical patterns.
On the receiving side, accounts collecting funds from multiple unrelated individuals and quickly moving those funds onwards may display characteristics consistent with scam collection or mule activity.
Other relevant indicators include repeated payments into connected beneficiary clusters, sudden increases in transaction frequency and beneficiaries linked to earlier scam complaints or suspicious counterparties.
No single indicator proves fraud. The stronger signal emerges when institutions connect customer behaviour, beneficiary activity, transaction velocity, scam intelligence and network relationships.
Why Financial Crime Intelligence Matters
This case illustrates a wider reality: financial crime is a network problem.
One institution may see an unusual customer payment. Another may see a beneficiary receiving funds from multiple individuals. A third may already have encountered the same romance-to-investment typology.
Viewed separately, each organisation sees only part of the threat.
Tookitaki is the intelligence ecosystem, helping financial institutions stay ahead of emerging financial crime threats. The AFC Ecosystem brings together typology intelligence, risk patterns and emerging threat insights from the financial crime community, allowing institutions to learn from patterns beyond those they have already encountered themselves.
A typology such as relationship-building followed by fraudulent investment solicitation can therefore become actionable intelligence rather than simply an after-the-fact case study.
FinCense turns that intelligence into control, helping institutions translate emerging typologies and risk patterns into deployable controls and adapt them as threats evolve.
The result is earlier threat visibility, faster control adaptation and greater confidence in responding to emerging financial crime patterns.
The Bigger Lesson: Follow the Network Behind the Trust
The Penang case is a reminder that the financial stage of a scam can begin long before money moves.
A Telegram conversation can become a relationship, and that relationship can later make a fraudulent investment opportunity appear credible. By the time the customer authorises a payment, the manipulation may already be deeply established.
For financial institutions, the stronger lesson is that social engineering at the front end can feed organised financial infrastructure at the back end.
One bank may see an authorised transfer. But when the beneficiary is receiving money from multiple victims or sits within a connected account network, the wider pattern can reveal what the individual payment cannot.
The relationship creates the trust. The beneficiary network turns that trust into proceeds.
Experience the most intelligent AML and fraud prevention platform
Experience the most intelligent AML and fraud prevention platform
Experience the most intelligent AML and fraud prevention platform
Top AML Scenarios in ASEAN
The Role of AML Software in Compliance
The Role of AML Software in Compliance