

Before the Money Moves
Faster payments need financial crime controls that keep pace.
Keep legitimate payments moving securely, with confidence that genuine risk is being identified before funds move.
See “Before the Money Moves” in Practice
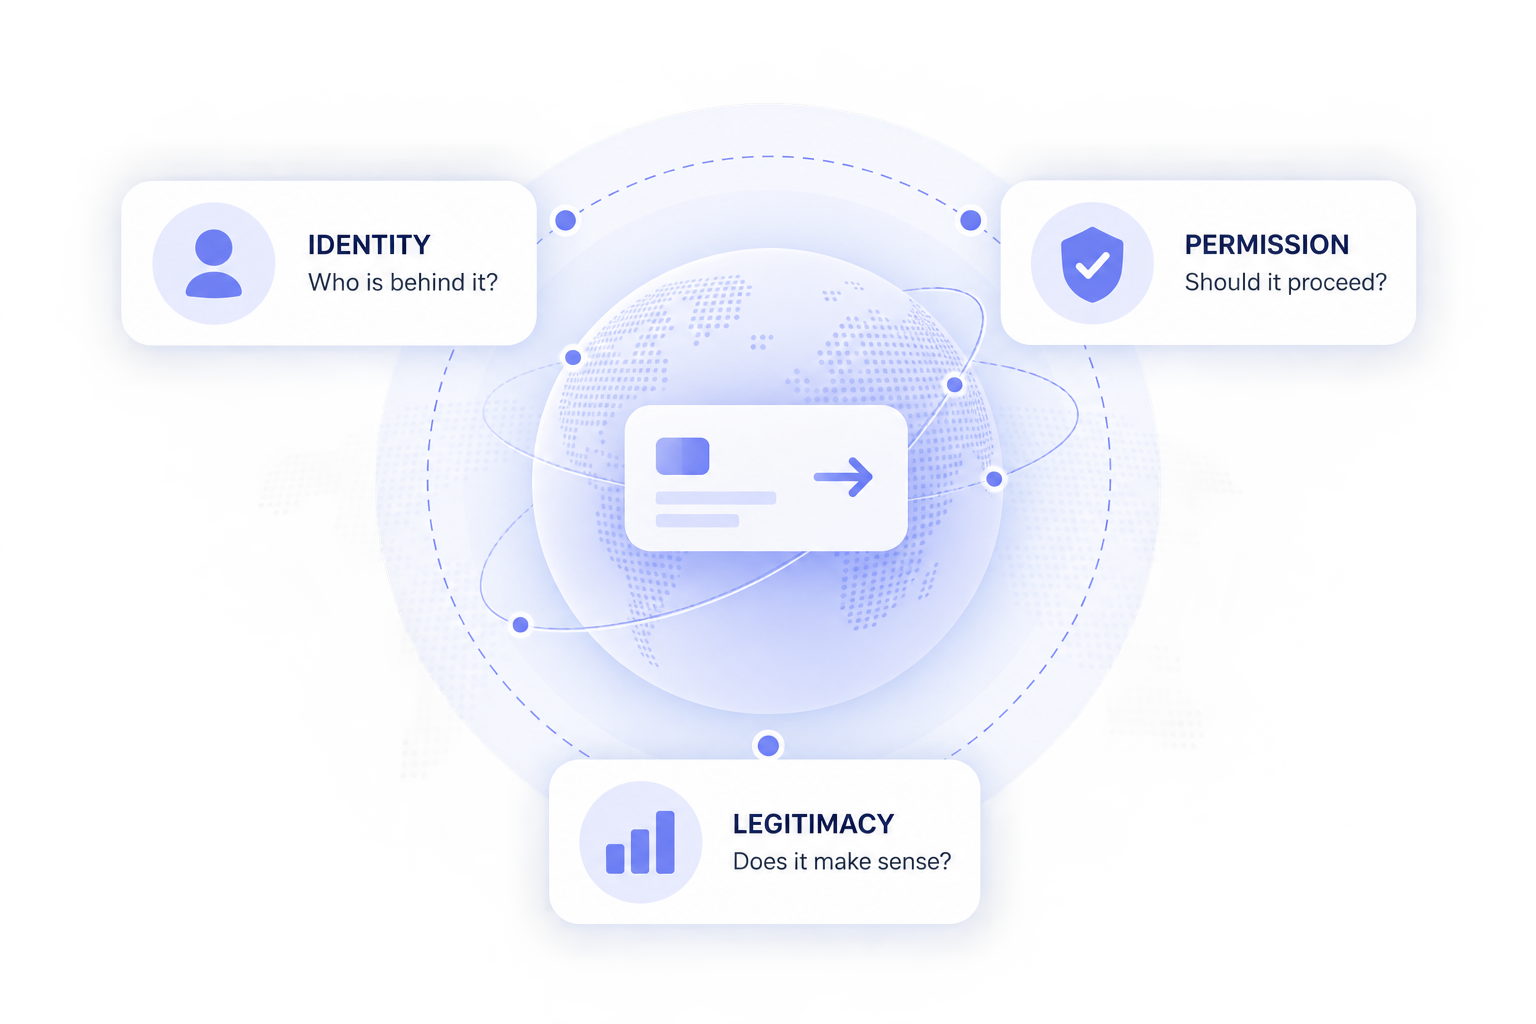
Join leaders from across the cross-border payments ecosystem to explore how Identity, Legitimacy and Permission come together inside the payment window and how connected controls can support each decision before the money moves.

Peter
Thunes

Josh Quinto
Chief Risk & Compliance Officer, PayMongo

Andy White
XXX
TENSION
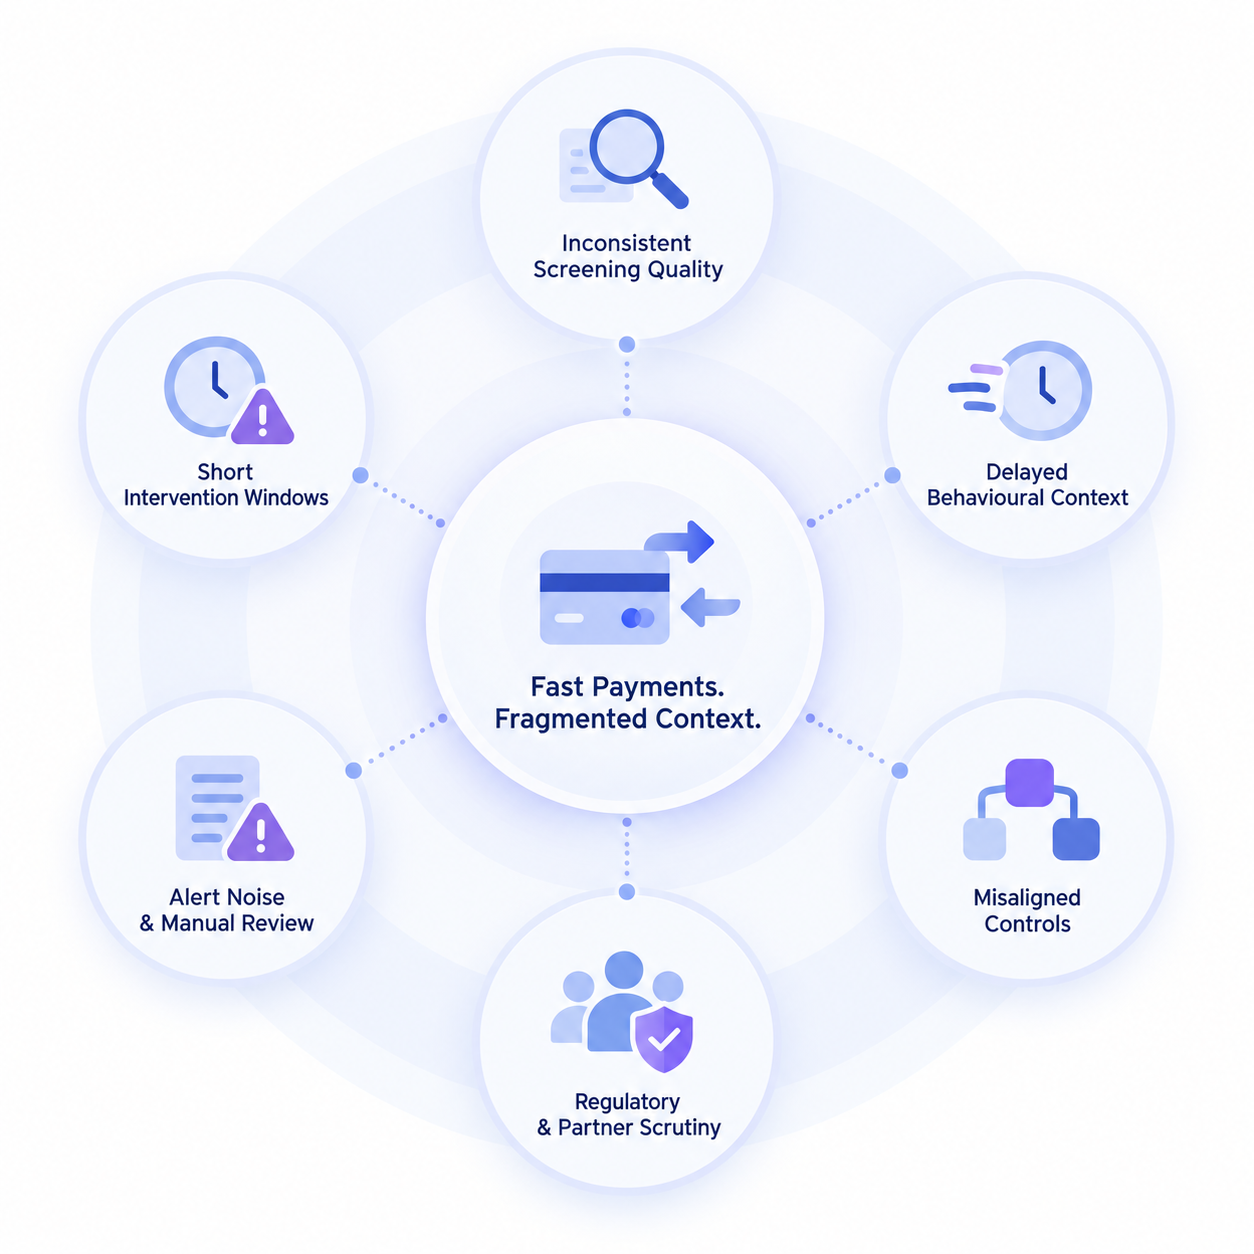
Fast Payments. Fragmented Context.
A payment can cross institutions, networks and jurisdictions in seconds, but the data and controls used to assess it often sit in separate systems, under different rules and risk appetites. Teams must resolve multiple issues while the customer is still waiting for the money to move.

80% Faster Deployment

100% Risk Coverage

50% Fewer False Positives

Flexible Deployment Options

50% reduction in investigation time

90% accuracy in high quality alerts
80% Faster Deployment
100% Risk Coverage
50% Fewer False Positives
Flexible Deployment Options
50% reduction in investigation time
90% accuracy in high quality alerts
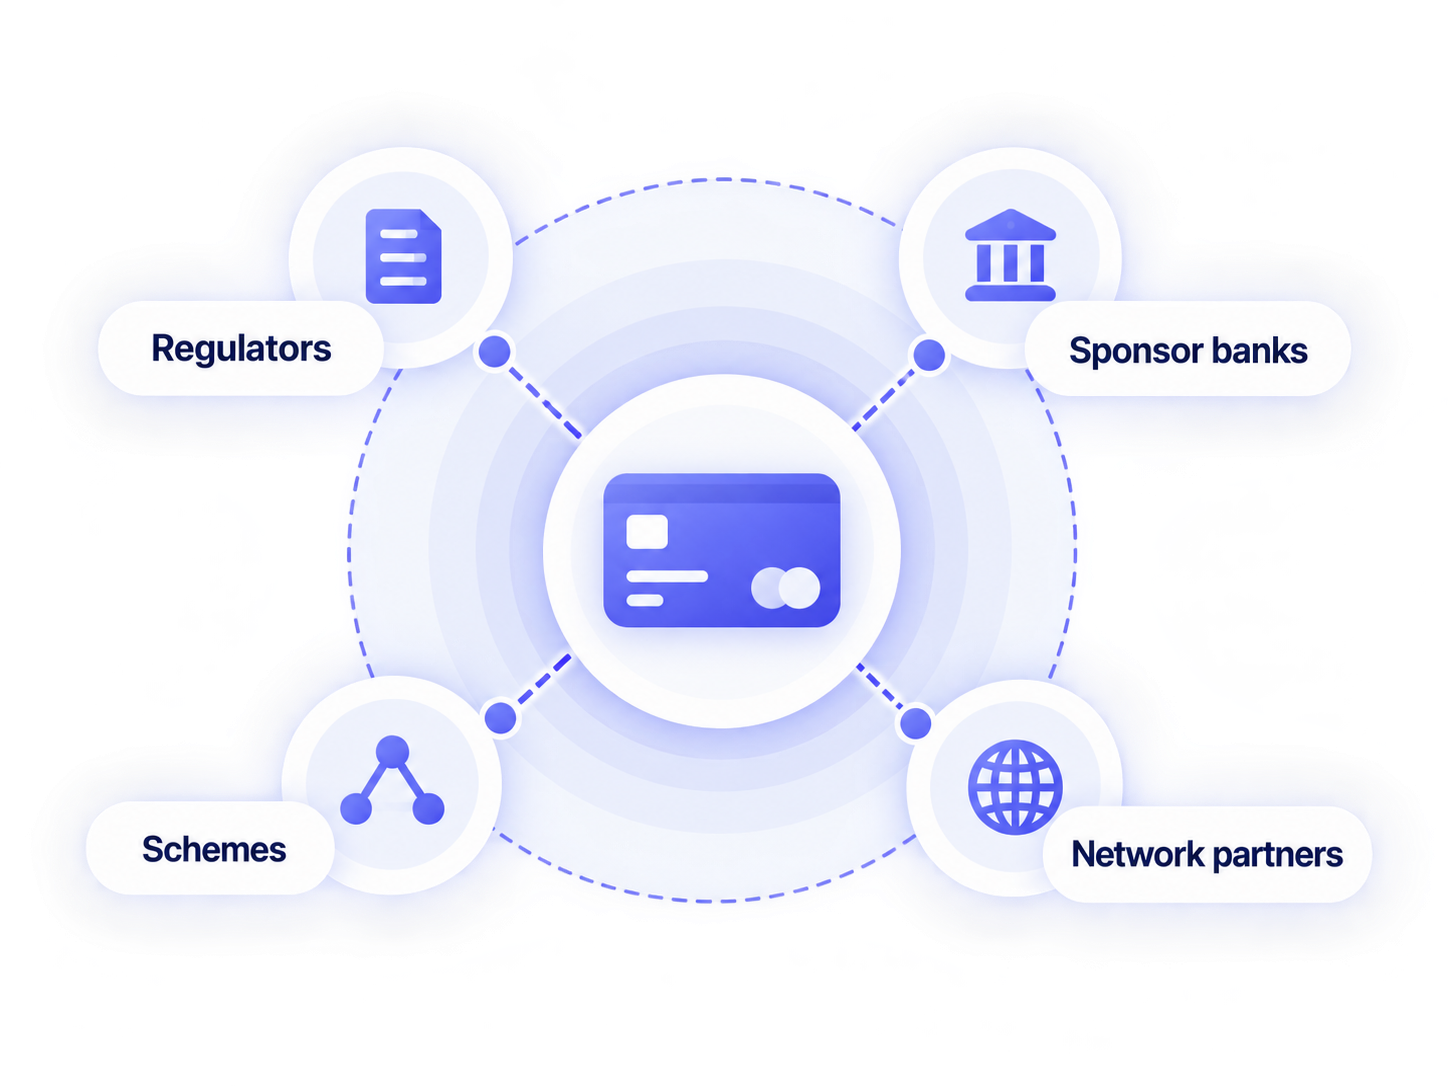
One Payment. Multiple Control Obligations.
80% Faster Deployment
100% Risk Coverage
50% Fewer False Positives
Flexible Deployment Options
50% reduction in investigation time
90% accuracy in high quality alerts
80% Faster Deployment
100% Risk Coverage
50% Fewer False Positives
Flexible Deployment Options
50% reduction in investigation time
90% accuracy in high quality alerts
Three Decisions. One Payment Window.
Effective cross-border control depends on three decisions being made together, using the same payment context.
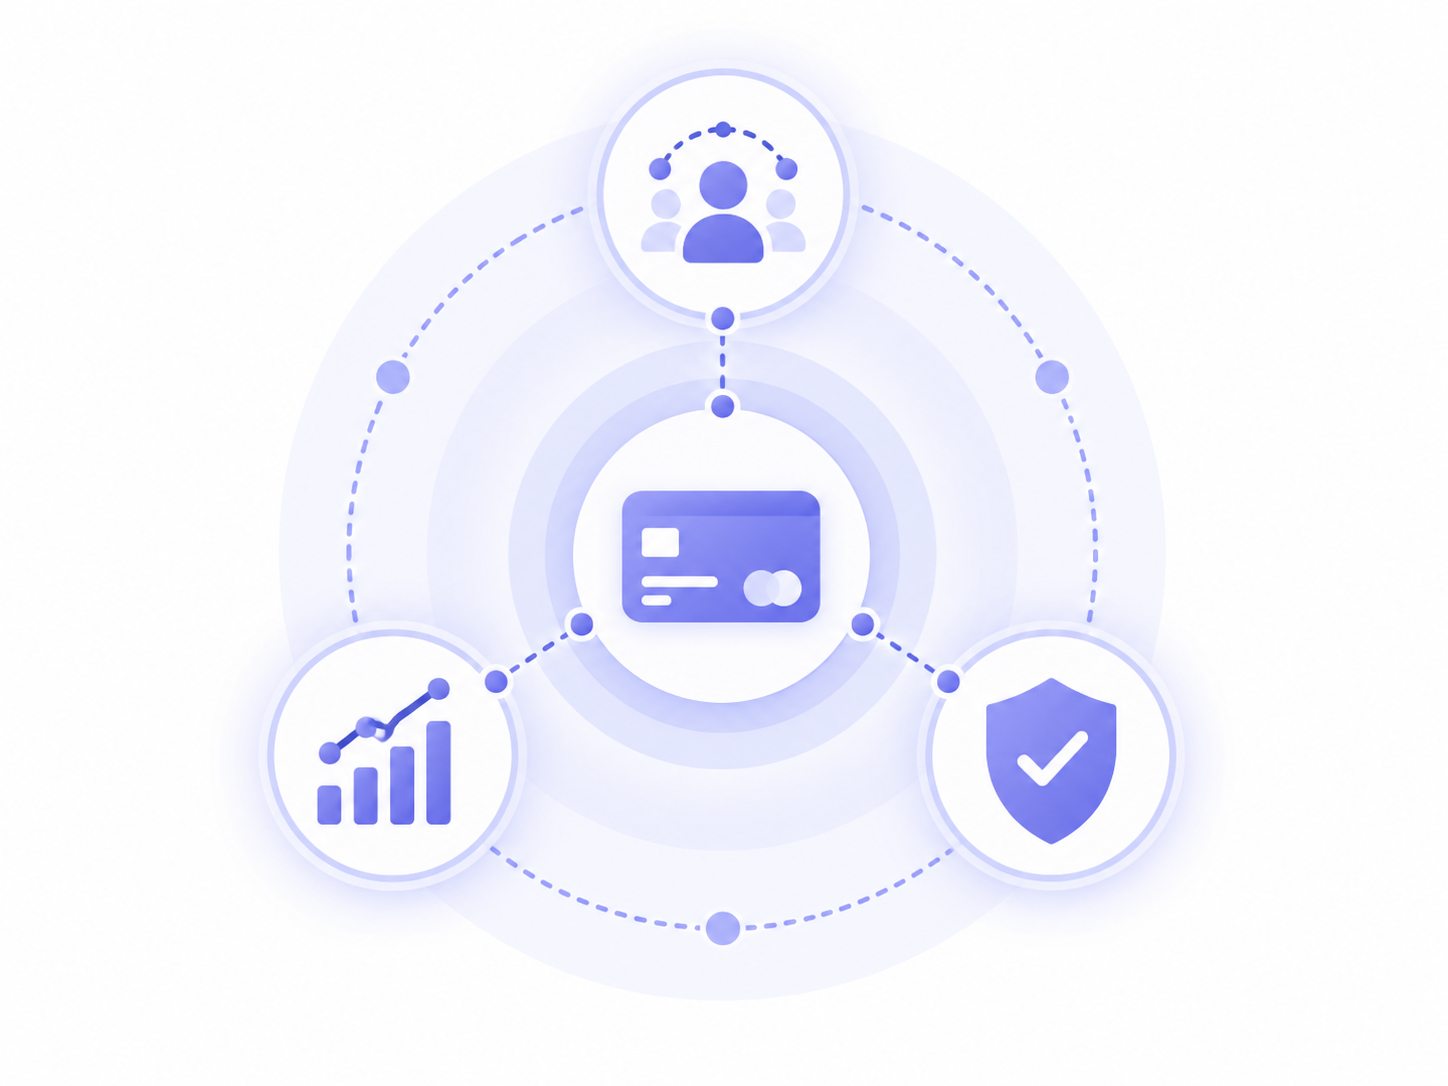
Who is really behind the payment?
Does the payment make sense in context?
Should the payment proceed?
80% Faster Deployment
100% Risk Coverage
50% Fewer False Positives
Flexible Deployment Options
50% reduction in investigation time
90% accuracy in high quality alerts
Intelligence Beyond Your Own
Transaction History
AFC intelligence brings emerging cross-border typologies and behavioural patterns into FinCense controls, helping institutions identify risk that may not yet be visible from their own transaction history.
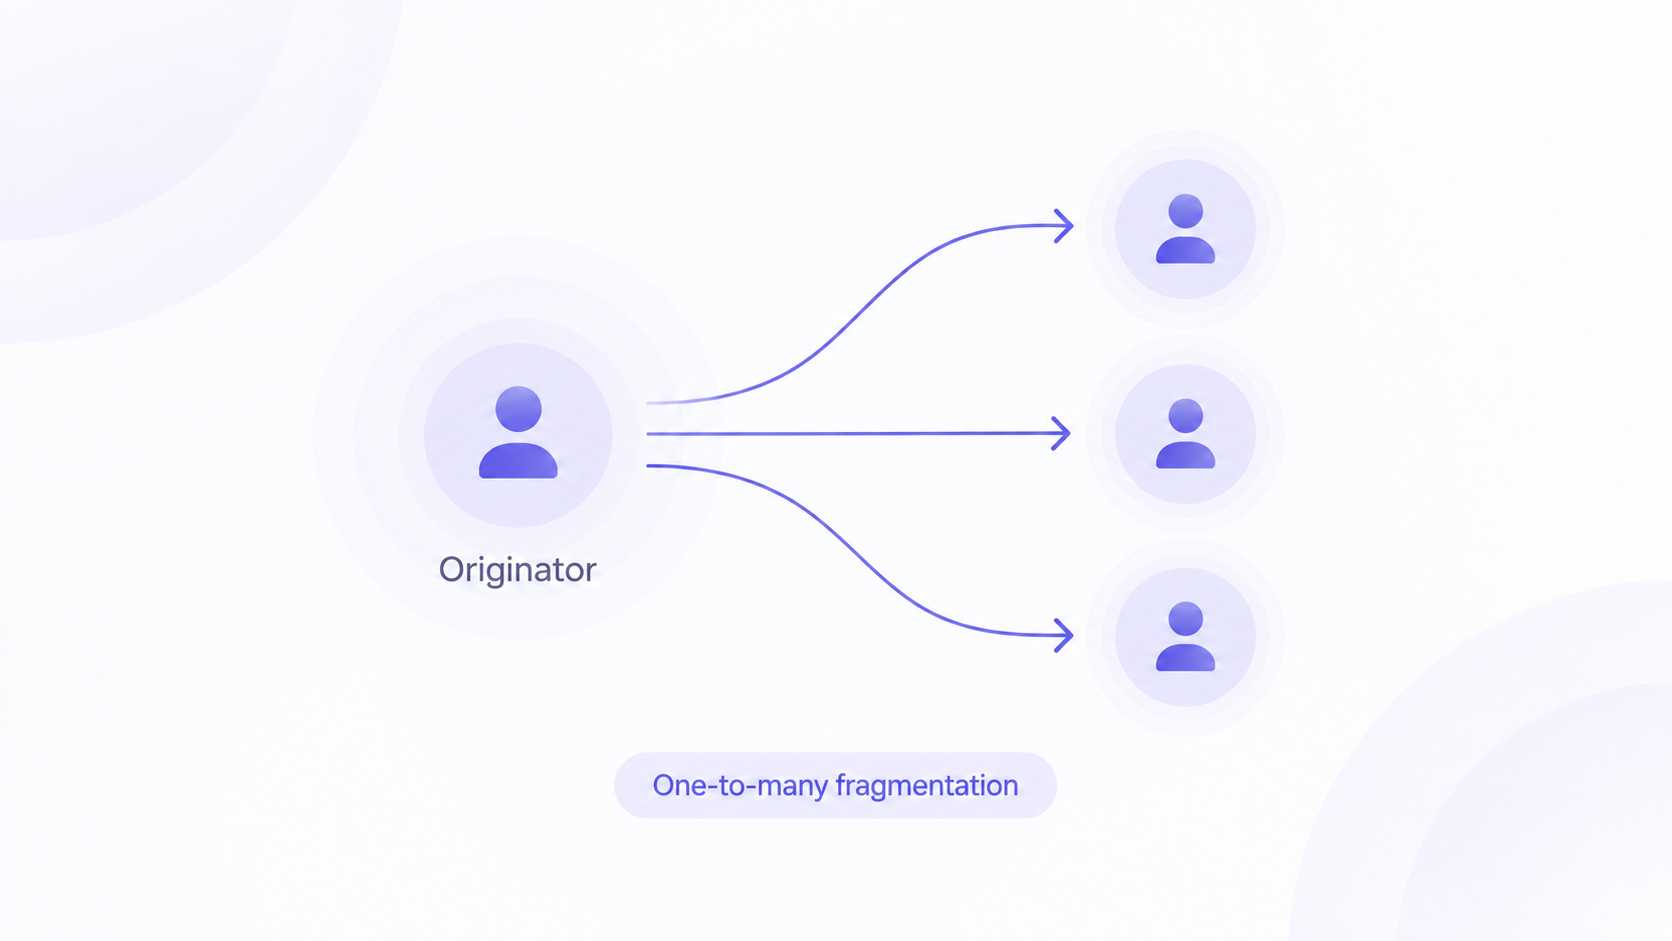
Drug-trafficking proceeds via smurfing
(One-to-many fragmentation)
Many transactions disperse funds across different recipients, revealing a structured pattern that may appear ordinary when each payment is viewed separately.
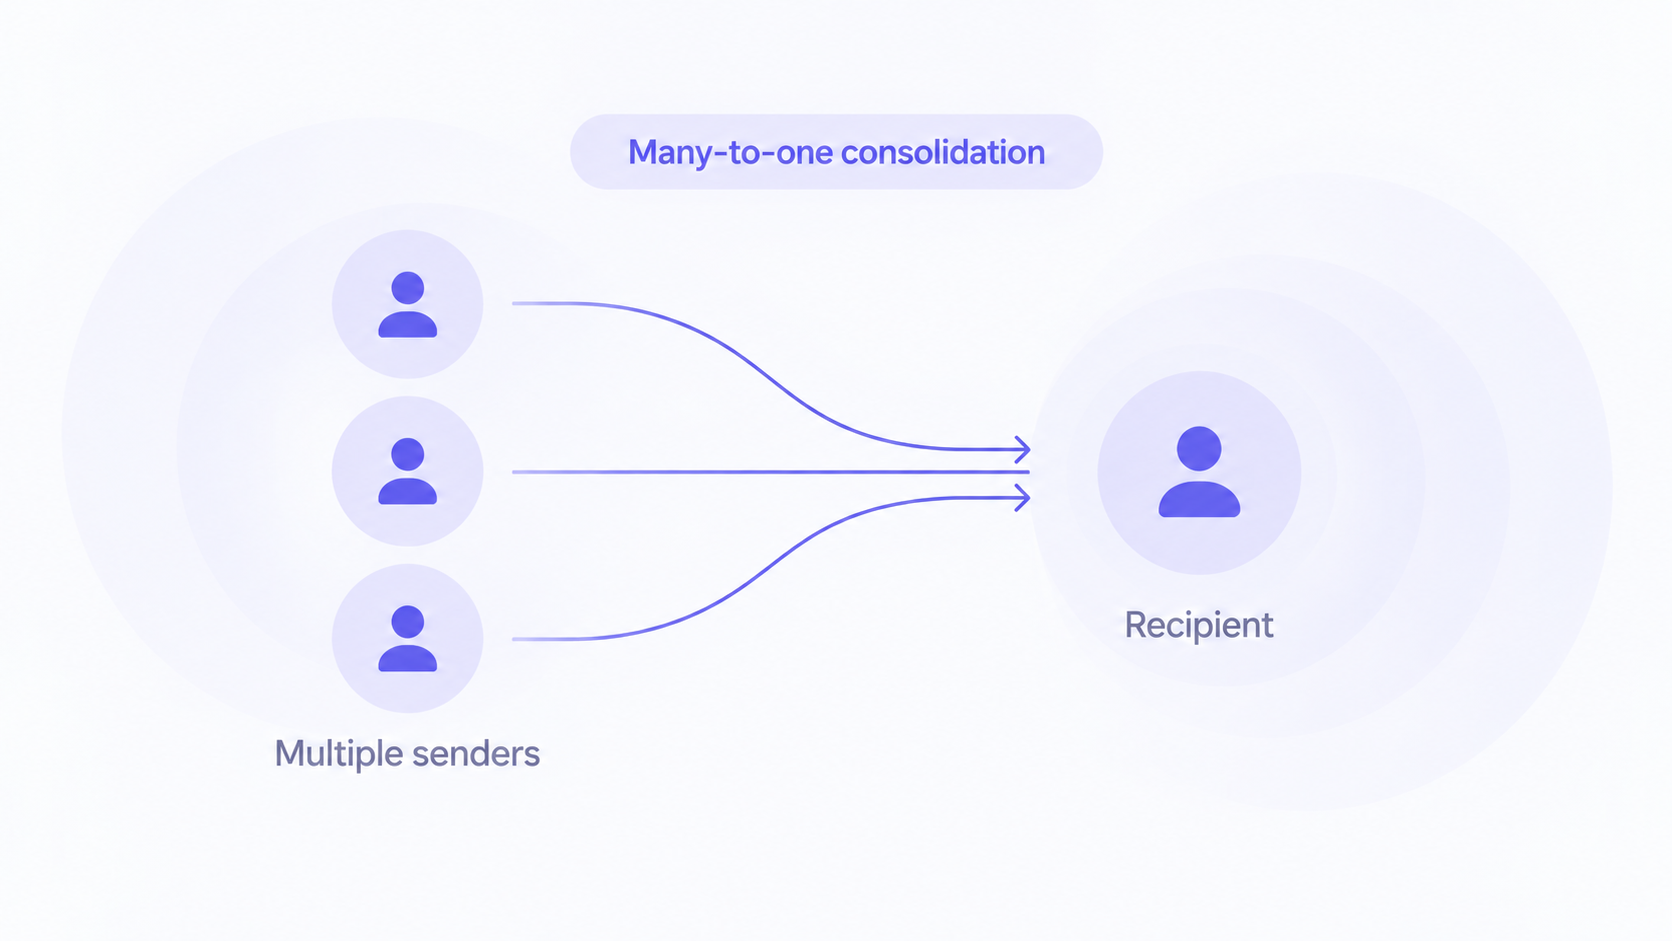
Inbound smurfing for suspected terrorism financing
(Many-to-one consolidation)
Multiple senders route funds into a single recipient, revealing coordinated funding activity that individual transactions may not expose.
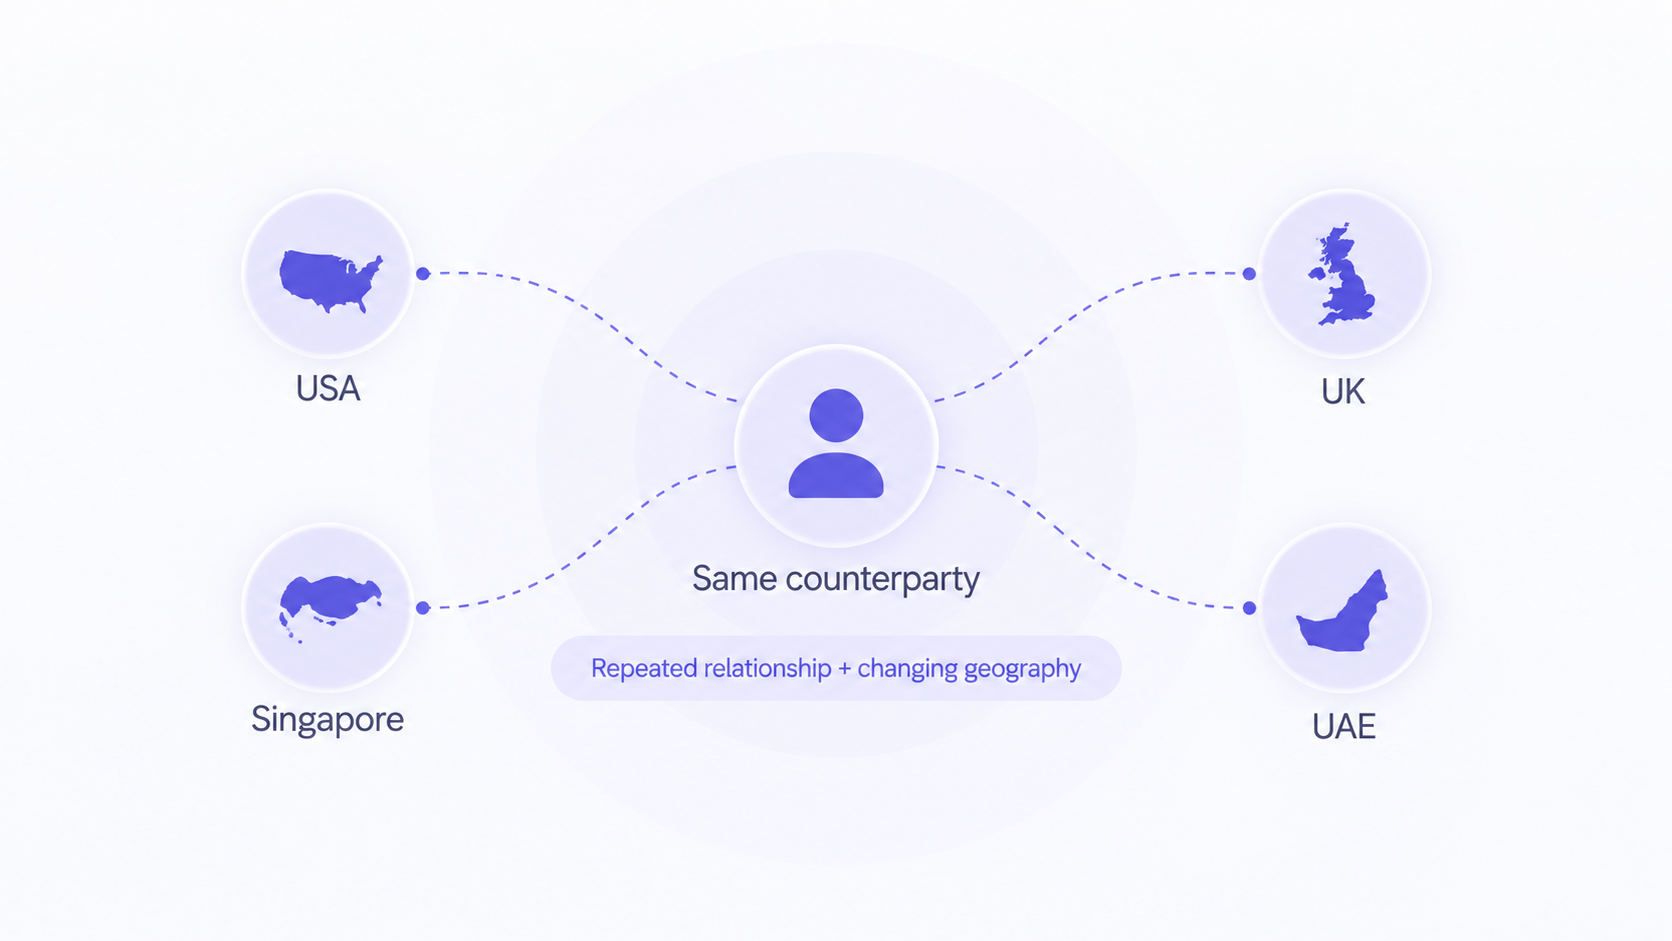
Same counterparty across multiple countries
(Repeated relationship + changing geography)
Recurring activity involving the same counterparty across jurisdictions can reveal suspicious cross-border behaviour over time.
80% Faster Deployment
100% Risk Coverage
50% Fewer False Positives
Flexible Deployment Options
50% reduction in investigation time
90% accuracy in high quality alerts
Turn the Three Decisions Into Connected Controls
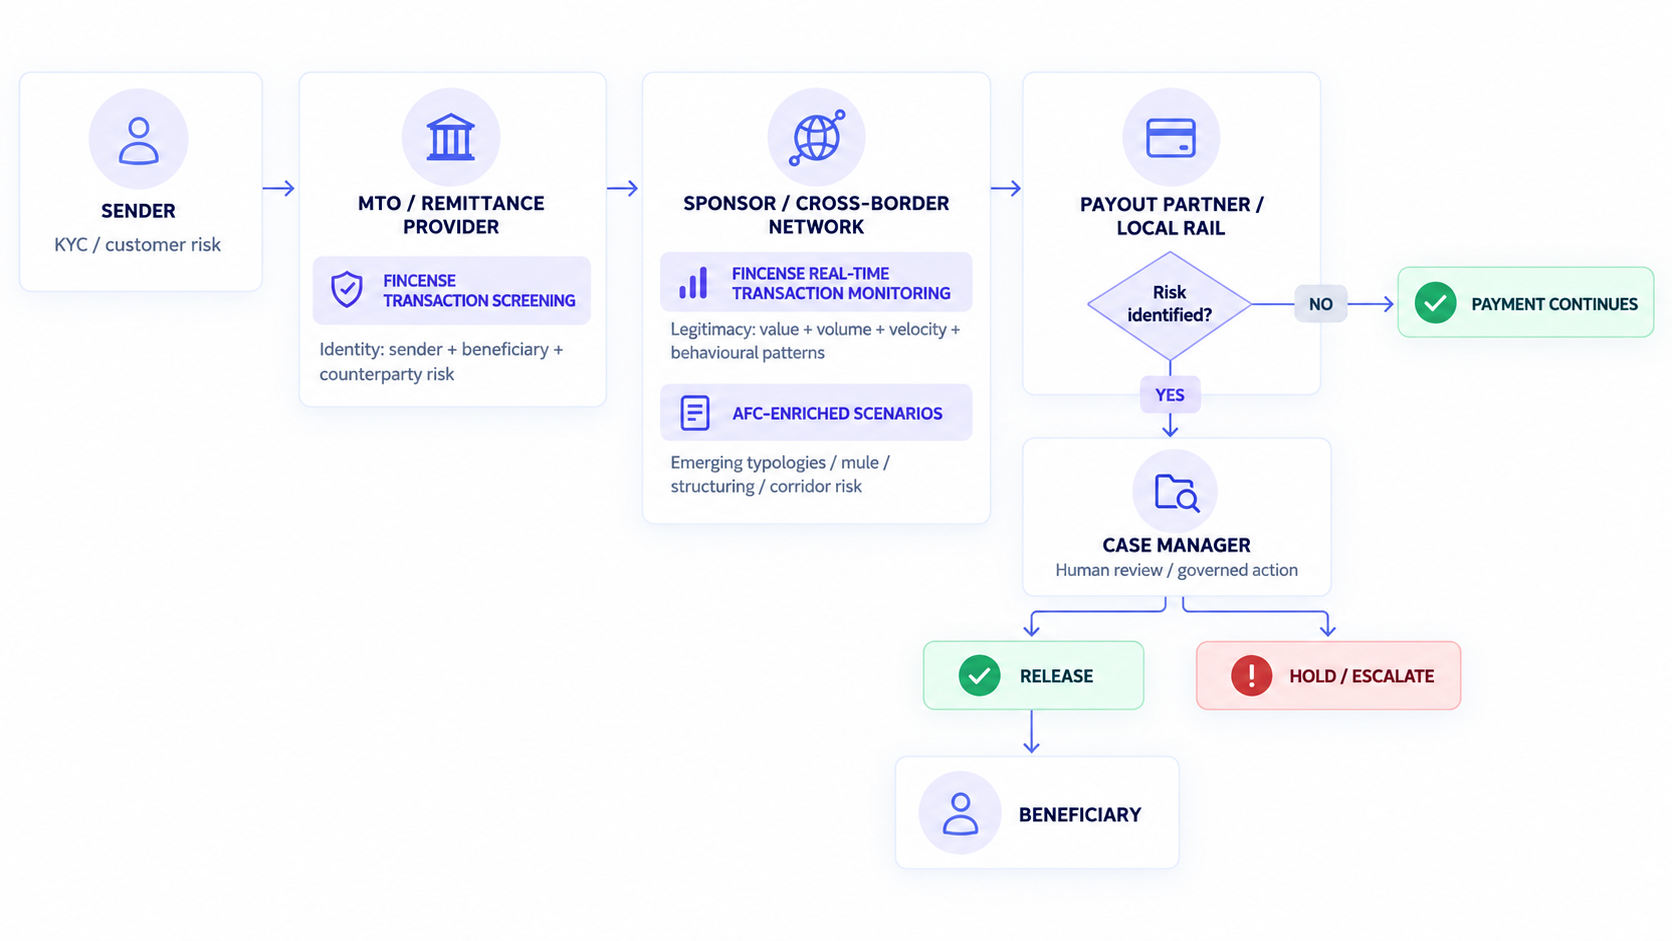
Real-Time Transaction Monitoring
- Assess behaviour and context as transactions happen
- Evaluate payment behaviour using institution-specific scenarios and evolving financial-crime typologies.

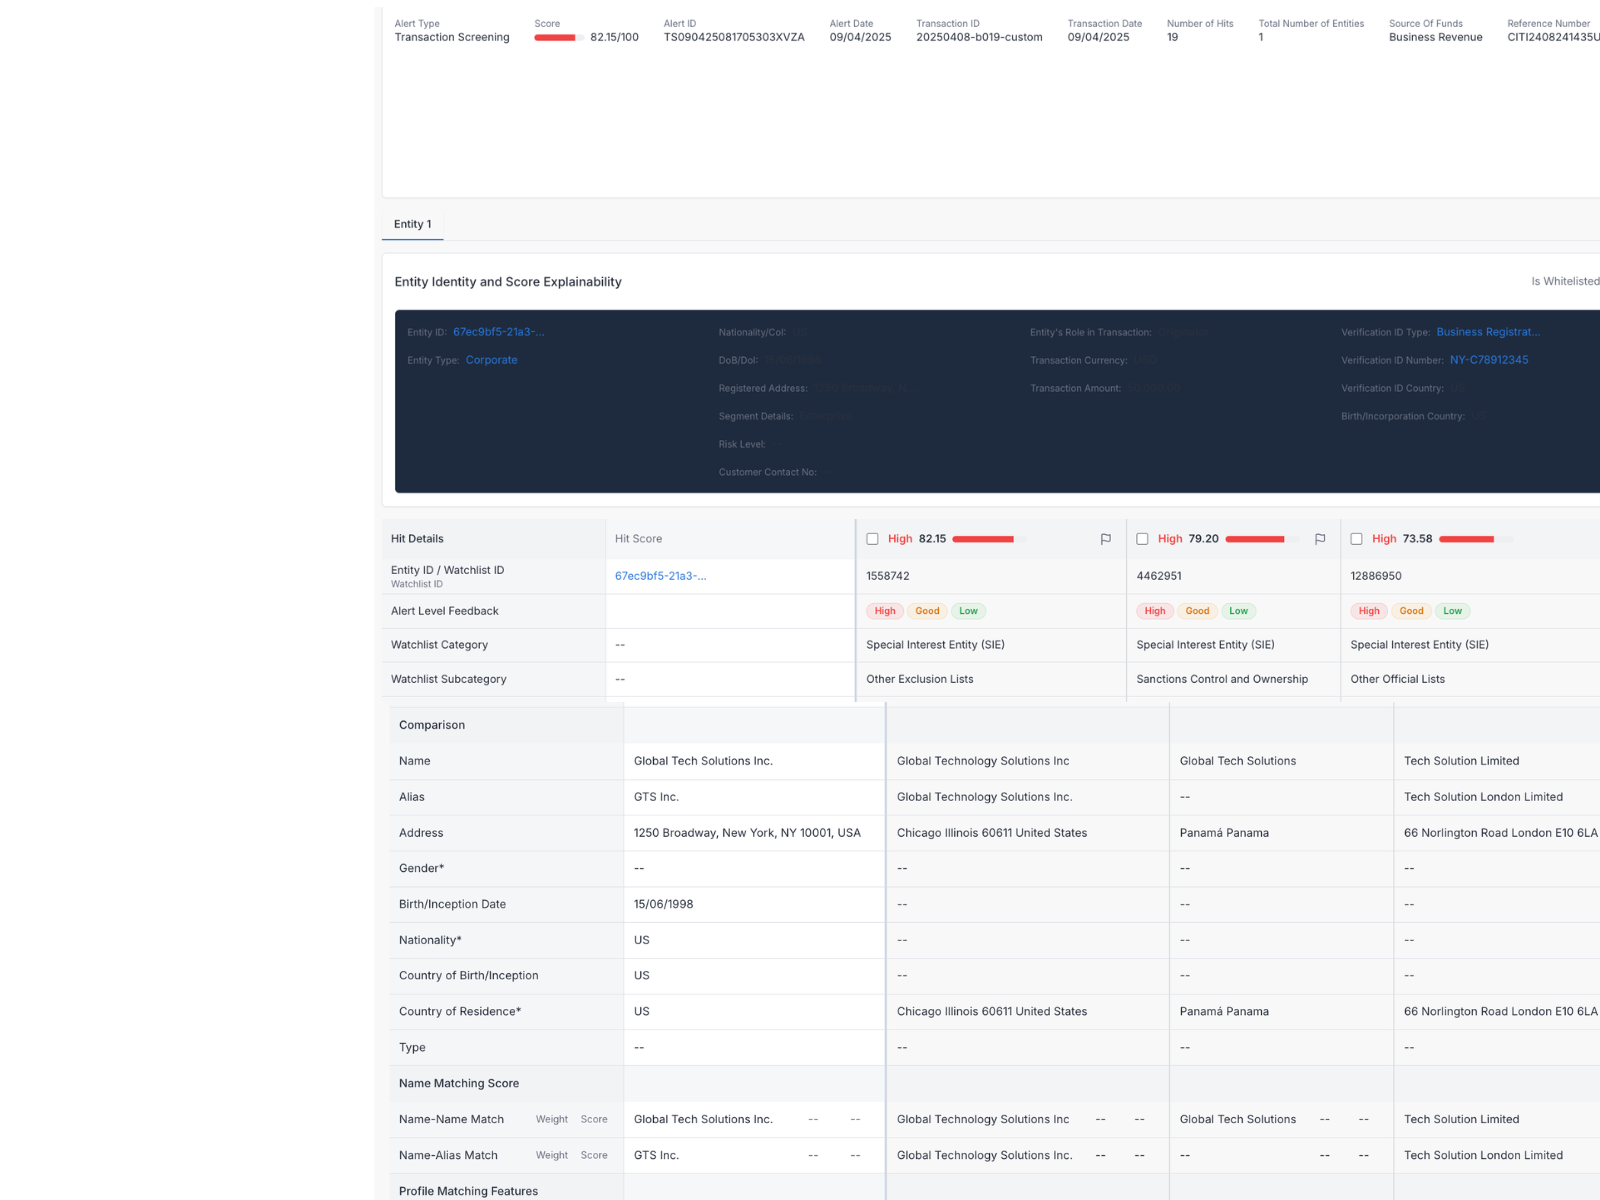
Transaction Screening
- Screen payment parties and information in real time.
- Screen originators, beneficiaries, intermediaries and payment information against sanctions, watchlists and other risk sources in real time.
Case Manager
- Centralise all transaction monitoring, screening and CDD alerts as a customer level case for effective investigation.
- Seamless reporting with automated STR and CTR reports as per local or goAML standards.

From Payment Initiation to Decision and
Exception Resolution
Proven at Digital-Payment Scale
Transactions monitored annually

120M+
Increase in Monitoring true positives per million transactions
5.6x
Reduction in Screening alert rate, run-rate to run-rate
64%
Reduction in effort on threshold tuning and scenario testing
70%
Reduction in false positives
90%
Partners Who Trust Us




Learn From Our Latest Thought Leadership Guides
Building a Future-Ready Community-Driven Compliance Model for a Leading Payment Processor
Roll out new AML measures quickly to support business expansion, while efficiently handling regulatory risks and keeping costs in check.
The client aimed to align its growth strategy with regulatory compliance requirements in regions like Singapore, Hong Kong, and Europe.
It faced the pressing need to scale up its financial crime compliance capabilities to support rapidly changing regulatory requirements, emerging money laundering threats and an expanding customer base.

Transforming Legacy Compliance system for a Universal Bank
Implementing a True Risk-based Approach and Reducing the Rising Cost of Compliance
UOB faced a strategic imperative to optimise its alert management and address the rising cost of compliance. With the volume and velocity of transactions flowing through the bank, there was a pressing need to reduce "false positives" and efficiently close alerts.
UOB was also keen to acquire better insights from the transactions and activities of high-risk individuals and companies and suspicious activities to remain vigilant against any potential money laundering activities. Having experimented with multiple systems, UOB faced challenges in finding a sustainable solution.
Building a Top-Grade Compliance System with Next-gen Technology for a Gen-Z Digital Bank
Meeting Stringent Regulatory Requirements to Launch Digital Banking Services in a Timely Manner
As a new entrant to the digital banking space, our client faced a unique set of challenges. The rules were clear: ensure full compliance with the Monetary Authority of Singapore (MAS) before their digital bank takes its maiden voyage.
To keep pace with the rapidly evolving landscape, they needed to onboard new transaction monitoring scenarios at lightning speed.
Building a Future-Ready Community-Driven Compliance Model for a Leading Payment Processor
Roll out new AML measures quickly to support business expansion, while efficiently handling regulatory risks and keeping costs in check.
The client aimed to align its growth strategy with regulatory compliance requirements in regions like Singapore, Hong Kong, and Europe.
It faced the pressing need to scale up its financial crime compliance capabilities to support rapidly changing regulatory requirements, emerging money laundering threats and an expanding customer base.
Transforming Legacy Compliance system for a Universal Bank
Implementing a True Risk-based Approach and Reducing the Rising Cost of Compliance
UOB faced a strategic imperative to optimise its alert management and address the rising cost of compliance. With the volume and velocity of transactions flowing through the bank, there was a pressing need to reduce "false positives" and efficiently close alerts.
UOB was also keen to acquire better insights from the transactions and activities of high-risk individuals and companies and suspicious activities to remain vigilant against any potential money laundering activities. Having experimented with multiple systems, UOB faced challenges in finding a sustainable solution.
Building a Top-Grade Compliance System with Next-gen Technology for a Gen-Z Digital Bank
Meeting Stringent Regulatory Requirements to Launch Digital Banking Services in a Timely Manner
As a new entrant to the digital banking space, our client faced a unique set of challenges. The rules were clear: ensure full compliance with the Monetary Authority of Singapore (MAS) before their digital bank takes its maiden voyage.
To keep pace with the rapidly evolving landscape, they needed to onboard new transaction monitoring scenarios at lightning speed.